Office Property
Seller-held mortgage or Wisconsin land contract: what is the difference for an office deal?
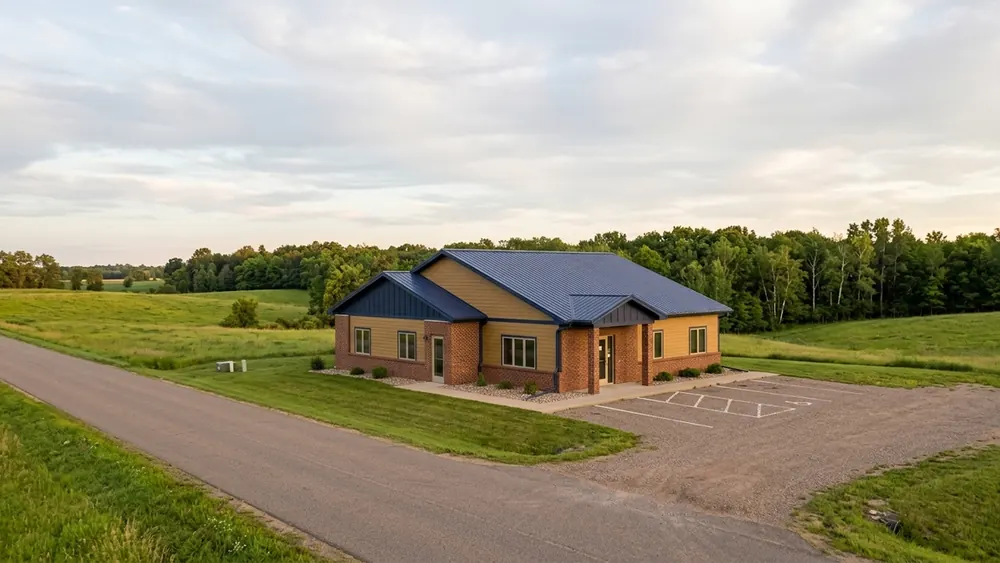
With a seller-held mortgage, the purchaser usually takes title at closing and the seller holds a mortgage. With a Wisconsin land contract, the purchaser pays the seller over time and receives full title once the contract terms are met.
On this page
- The core difference in plain terms
- Why seller financing comes up on office deals
- How a seller-held mortgage works
- How a Wisconsin land contract works
- Questions to settle before choosing a structure
- Comparing the two side by side
- How the building affects the financing choice
- Next steps before you talk terms
The core difference in plain terms
Both a seller-held mortgage and a Wisconsin land contract let the seller of an office building finance part or all of the sale instead of a bank. The core difference is title. With a seller-held mortgage, the purchaser usually takes title at closing and the seller holds a mortgage on the property, much as a bank would. With a land contract, the purchaser typically makes payments to the seller over time and receives full title once the contract terms are met.
That difference matters because title affects who carries which risks during the life of the deal. It can shape what happens if payments stop, who is responsible for taxes, insurance and upkeep, and how easily the purchaser can refinance or sell later. Two deals with the same price and the same payment can feel very different depending on which structure sits underneath them, so it pays to understand both before negotiating.
This article explains the two structures as concepts, so you can follow the conversation and ask better questions. It is not legal or tax advice. Seller financing carries legal and tax consequences in Wisconsin, and the specifics of any office deal should be reviewed by a Wisconsin attorney, a lender and an accountant before anyone signs. Guy can help you think through the real estate side and how the structure fits the building.
Why seller financing comes up on office deals
Seller financing tends to come up when bank financing is hard to arrange, when a seller wants income spread over time, or when a building’s leases or condition make a lender cautious. Around Eau Claire, as elsewhere, an older office building with some vacant suites may draw more questions from a bank than a buyer expects. In those situations, a seller who is willing to carry part of the financing can help a deal come together.
That flexibility cuts both ways. A seller who finances the sale keeps a stake in how the building performs, and a purchaser takes on obligations to the seller instead of to a bank. Neither structure is automatically better. The right choice depends on the building, the people involved and how much risk each side is comfortable carrying, which is why the terms deserve as much attention as the price.
Read the default terms before you fall for the payment. How a deal ends when something goes wrong matters as much as how it starts.
How a seller-held mortgage works
With a seller-held mortgage, the sale closes much like a conventional purchase. The purchaser receives the deed and becomes the owner of record. Instead of borrowing all of the money from a bank, the purchaser signs a promissory note to the seller, which is a written promise to repay, and the seller records a mortgage against the property as security. The purchaser then makes payments to the seller under the terms of that note.
Because the purchaser holds title, the purchaser generally carries the responsibilities of ownership from the start: taxes, insurance, maintenance and the relationship with tenants. The seller’s protection is the mortgage. If payments stop, the seller’s remedies run through that mortgage, and how that process works in Wisconsin is a question for your attorney, not something to assume from a summary or from how another deal was handled.
A seller-held mortgage can sit alongside a bank loan, with the bank in first position and the seller behind it, or it can stand alone. If a bank is involved, it will have its own requirements about any second mortgage, so talk to the lender early. The order of the loans, and what each lender can do if something goes wrong, needs to be clear on paper before closing, not worked out afterward.
How a Wisconsin land contract works
With a Wisconsin land contract, the seller typically keeps legal title while the purchaser takes possession and makes payments over time. Once the contract is paid or its terms are met, the seller delivers the deed and full title passes to the purchaser. In the meantime, the purchaser usually holds what is often described as an equitable interest in the property, meaning a real stake that grows as the contract is performed.
The contract itself spells out who pays taxes and insurance, who handles repairs, what happens if a payment is missed, and whether the purchaser can make improvements or sign new leases with tenants. On an office building, those last points matter a great deal, because leasing decisions shape what the building is worth. A Wisconsin attorney should explain what remedies each side has under the contract before you agree to it.
Questions to settle before choosing a structure
Whichever structure is on the table, a handful of questions decide whether it works for you. Write them down before you start negotiating, and make sure each one has a clear answer in the documents rather than in a conversation. These are not the only questions worth asking, but they are the ones that most often cause trouble when they are left vague or settled with a handshake.
- Who pays property taxes, insurance and building repairs while payments are being made
- What counts as a default, and what notice and chance to fix it each side gets
- Whether the purchaser can refinance, sell or sign new tenant leases before payoff
- Whether any existing mortgage on the property allows the seller to finance the sale
That last question is easy to miss. If the seller still owes a bank on the building, the existing loan may limit what the seller can agree to. An attorney and a lender can check that early. Getting these answers in writing protects both sides, and it gives the deal a better footing for the surprises that can come with owning and operating an office building over a long payment period.
Comparing the two side by side
A side-by-side view can make the differences easier to hold in your head. The table below compares the two structures on the points that most often come up in an office deal. It describes general concepts, and the actual terms in any contract can vary widely. Use it as a starting point for your questions, then confirm every point with a Wisconsin attorney for the specific deal you are considering.
| Point | Seller-held mortgage | Land contract |
|---|---|---|
| Who holds title | The purchaser, from closing | The seller, until the contract terms are met |
| Seller’s security | A recorded mortgage on the property | Keeping legal title during the contract |
| Ownership costs | Usually the purchaser, as owner of record | Set by the contract, often the purchaser |
| Leasing decisions | Usually the purchaser’s call as owner | Depends on what the contract allows |
| If payments stop | Remedies run through the mortgage; ask your attorney | Depends on the contract; ask your attorney |
Notice how many rows depend on the contract. That is the main lesson of the comparison. Labels like seller-held mortgage and land contract describe the general shape of a deal, but the documents decide the details. Two land contracts can look quite different from each other, and so can two seller-held mortgages. Read the actual terms rather than relying on the label, and ask about anything that is not spelled out.
How the building affects the financing choice
The office building itself should shape how you think about either structure. A roof near the end of its life, aging mechanical systems or leases ending close together all mean more risk during the payment period, for both sides. Before you agree to terms, walk the building, review the leases and line up a qualified building inspector. The financing has to fit the property and its tenants, not just the price on the page.
This is where a background in construction and site selection helps on the real estate side. Guy looks at the building and the leases alongside the deal structure, so a financing conversation does not happen in isolation from the roof, the tenants and the parking. Seller-held mortgages and Wisconsin land contracts for office deals are a regular LinkedIn topic, always with a clear line on when an attorney, lender or accountant should weigh in.
Next steps before you talk terms
Before you discuss seller financing on an office building in Eau Claire, gather what you can. Write down the building you are considering, why you want it, and whether you plan to occupy it, lease it out or both. Note what you know about the leases and the condition. Then line up a Wisconsin attorney, a lender and an accountant, because each of them will have a role once real terms are on the table.
If you are weighing a seller-held mortgage against a land contract, or a seller has raised one of them, bring the deal to Guy. A first conversation is a chance to look at the building, the leases and how the financing could be structured, and to sort out which questions belong to your attorney, lender or accountant. There is no pressure to decide anything, just a clearer picture before you commit.
This article is general information about commercial property and land in Eau Claire and Wisconsin. It is not legal, tax, lending, investment, valuation or inspection advice and does not predict prices, rents or returns. Confirm zoning and permitted uses with the city, town or county, leases and contracts with an attorney, financing with a lender, taxes and valuation with an accountant, and building condition with a qualified inspector. Guy Rossato, Guy Rossato Real Estate LLC.
Written by